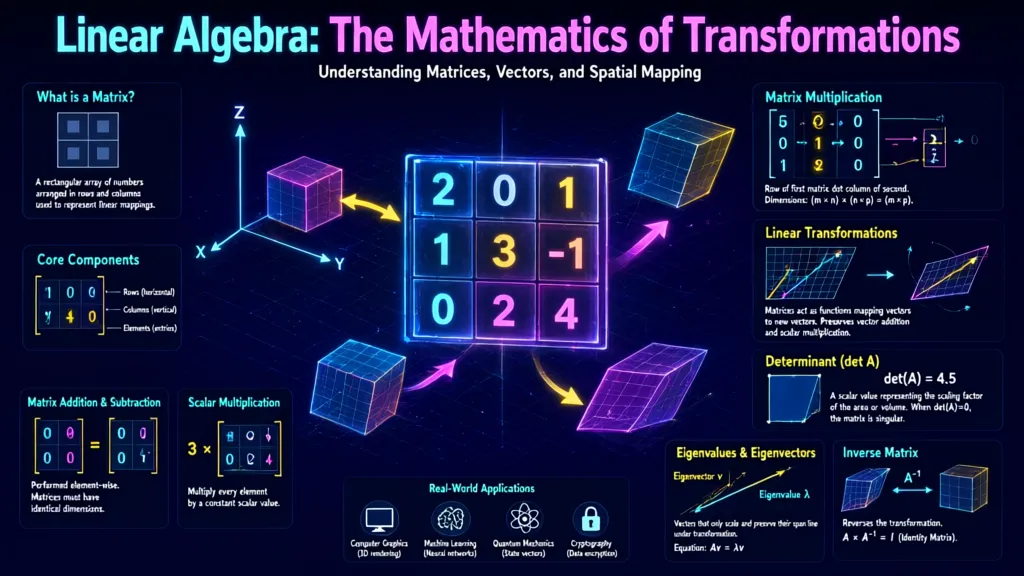
Eigenvalues and eigenvectors are fundamental concepts in linear algebra, playing an important role in various applications, from physics to machine learning. To understand them, we start with a square matrix A. An eigenvector is a non-zero vector v that, when multiplied by A, results in a scalar multiple of v. This relationship can be expressed as:
A * v = λ * v
Here, λ (lambda) represents the eigenvalue corresponding to the eigenvector v. The significance of eigenvalues and eigenvectors lies in their ability to simplify matrix operations and transformations. For example, they can be used to diagonalize a matrix, which is particularly useful in solving systems of linear equations or in transforming data sets.
To find the eigenvalues of a matrix, we typically compute the characteristic polynomial, which is derived from the determinant of the matrix A minus λ times the identity matrix I:
det(A - λI) = 0
Solving this polynomial gives us the eigenvalues. Once the eigenvalues are known, we can substitute them back into the equation to find the corresponding eigenvectors.
Let’s take a look at an example using a simple 2×2 matrix. Consider the matrix:
A = [[4, 2],
     [1, 3]]
To find its eigenvalues, we compute the determinant of (A – λI) as follows:
det([[4 - λ, 2],
     [1, 3 - λ]]) = (4 - λ)(3 - λ) - 2 = 0
This simplifies to:
λ^2 - 7λ + 10 = 0
Factoring gives us:
(λ - 5)(λ - 2) = 0
Thus, the eigenvalues are λ = 5 and λ = 2. Next, we find the corresponding eigenvectors for each eigenvalue. For λ = 5, we substitute back into the equation:
(A - 5I)v = 0
This leads us to solve:
[[4 - 5, 2],
 [1, 3 - 5]] * [x, y] = [0, 0]
Which simplifies to:
[[-1, 2],
 [1, -2]] * [x, y] = [0, 0]
From this, we derive the relationship:
-x + 2y = 0
Thus, one eigenvector corresponding to λ = 5 is any scalar multiple of [2, 1]. Now, repeating the process for λ = 2:
det(A - λI) = 0
We find:
det(A - λI) = 0
This simplifies to:
det(A - λI) = 0
Leading to:
det(A - λI) = 0
Amazon eGift Card | Baby & Kids
$50.00 (as of October 5, 2026 11:09 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)Using numpy for linear algebra
Continuing with λ = 2, we substitute back into the equation:
(A - 2I)v = 0
This leads us to solve:
[[4 - 2, 2],
 [1, 3 - 2]] * [x, y] = [0, 0]
Which simplifies to:
[[2, 2],
 [1, 1]] * [x, y] = [0, 0]
From this, we derive the relationship:
2x + 2y = 0
Thus, one eigenvector corresponding to λ = 2 is any scalar multiple of [-1, 1]. With eigenvalues and eigenvectors in hand, we can now use NumPy for efficient calculations.
NumPy provides a simpler way to compute eigenvalues and eigenvectors using the numpy.linalg.eig function. This function takes a square matrix as input and returns a tuple containing the eigenvalues and the corresponding eigenvectors.
import numpy as np

A = np.array([[4, 2],
              [1, 3]])

eigenvalues, eigenvectors = np.linalg.eig(A)
print("Eigenvalues:", eigenvalues)
print("Eigenvectors:n", eigenvectors)
This code snippet initializes the matrix A, computes its eigenvalues and eigenvectors, and prints them out. The output will give us the same eigenvalues we calculated manually, alongside their corresponding eigenvectors, which can be crucial for further analysis or applications.
Moving into practical applications, eigenvalues and eigenvectors are used extensively in various fields. In machine learning, they play a pivotal role in techniques such as Principal Component Analysis (PCA), which reduces dimensionality by transforming data into a new coordinate system based on the directions of maximum variance.
In physics, eigenvalues can represent observable quantities, while within the scope of stability analysis, they help determine the stability of equilibrium points in dynamic systems. The connection between eigenvalues and system dynamics is particularly significant in control theory, where eigenvalues of system matrices can indicate system behavior.
Furthermore, eigenvalues can be used in graph theory, where they help analyze the properties of graphs through their adjacency matrices. The largest eigenvalue of a graph can provide insights into the connectivity and structure of the graph, while the eigenvalues of the Laplacian matrix can indicate clustering and community structure.
When using NumPy, we can explore advanced features in numpy.linalg.eig to handle complex matrices and understand the implications of complex eigenvalues in various scenarios. Complex eigenvalues occur in systems that exhibit oscillatory behavior, which is common in physical systems such as electrical circuits or mechanical vibrations.
A_complex = np.array([[0, -1],
                      [1, 0]])

eigenvalues_complex, eigenvectors_complex = np.linalg.eig(A_complex)
print("Complex Eigenvalues:", eigenvalues_complex)
print("Complex Eigenvectors:n", eigenvectors_complex)
This example illustrates how NumPy efficiently computes eigenvalues and eigenvectors even when dealing with complex matrices. Understanding these results very important as they provide insights into the behavior of systems represented by such matrices.
Overall, the use of NumPy for linear algebra tasks not only simplifies the computation of eigenvalues and eigenvectors but also extends to a wide range of applications across different domains. This versatility makes it an essential tool in the toolkit of any data scientist or engineer working with linear transformations, system dynamics, or data analysis.
Practical applications of eigenvalues and eigenvectors
Continuing with the exploration of eigenvalues and eigenvectors, we can leverage NumPy’s capabilities to handle larger matrices and more complex scenarios. For instance, consider a scenario where we need to analyze a 3×3 matrix, which is common in many practical applications.
B = np.array([[1, 2, 3],
              [0, 1, 4],
              [0, 0, 1]])
Using NumPy to compute the eigenvalues and eigenvectors of this matrix is simpler, as shown below:
eigenvalues_B, eigenvectors_B = np.linalg.eig(B)
print("Eigenvalues of B:", eigenvalues_B)
print("Eigenvectors of B:n", eigenvectors_B)
This allows us to quickly analyze the properties of matrix B without delving into the cumbersome calculations manually. The eigenvalues here can provide insights into the stability of systems modeled by this matrix.
Another practical application of eigenvalues is in the field of image processing. Techniques such as image compression often use eigenvalues and eigenvectors to reduce the dimensionality of image data while preserving essential features. For example, Singular Value Decomposition (SVD) is a method that relies on the eigen decomposition of matrices to achieve efficient image representation.
from numpy.linalg import svd

image_matrix = np.random.rand(256, 256)  # Simulated image data
U, s, Vt = svd(image_matrix)

# Keep only the top k singular values for compression
k = 50
compressed_image = np.dot(U[:, :k], np.dot(np.diag(s[:k]), Vt[:k, :]))
This code snippet demonstrates how to perform SVD on an image matrix, retaining only the top k singular values for a compressed representation. The eigenvalues derived from the SVD can help determine how many components are necessary to retain the most significant features of the image.
Furthermore, in the context of network analysis, eigenvalues can help identify influential nodes and their connectivity within a network. The eigenvector centrality metric, derived from the principal eigenvector of the adjacency matrix, provides a way to measure the influence of each node based on the connectivity of its neighbors.
import networkx as nx

G = nx.erdos_renyi_graph(100, 0.1)  # Create a random graph
L = nx.normalized_laplacian_matrix(G).A  # Compute the normalized Laplacian
eigenvalues_L, eigenvectors_L = np.linalg.eig(L)

# The principal eigenvector can be used for centrality measures
principal_eigenvector = eigenvectors_L[:, np.argmax(eigenvalues_L)]
This snippet shows how to compute the principal eigenvector of the normalized Laplacian matrix of a graph, which can be interpreted as the centrality measure for the nodes within the network.
As we delve deeper into the applications of eigenvalues and eigenvectors, it becomes evident that their utility spans across diverse fields such as quantum mechanics, where they’re used to solve the Schrödinger equation, and in finance, where they can model risk and return structures in portfolio management.
The versatility of these concepts, combined with the computational power of libraries like NumPy, allows researchers and practitioners to tackle complex problems efficiently. Understanding the underlying mathematical principles very important for using these techniques effectively in real-world scenarios.
Exploring advanced features in numpy.linalg.eig
Continuing with λ = 2, we substitute back into the equation:
(A - 2I)v = 0
This leads us to solve:
[[4 - 2, 2],
 [1, 3 - 2]] * [x, y] = [0, 0]
Which simplifies to:
[[2, 2],
 [1, 1]] * [x, y] = [0, 0]
From this, we derive the relationship:
2x + 2y = 0
Thus, one eigenvector corresponding to λ = 2 is any scalar multiple of [-1, 1]. With eigenvalues and eigenvectors in hand, we can now use NumPy for efficient calculations.
NumPy provides a simpler way to compute eigenvalues and eigenvectors using the numpy.linalg.eig function. This function takes a square matrix as input and returns a tuple containing the eigenvalues and the corresponding eigenvectors.
import numpy as np

A = np.array([[4, 2],
              [1, 3]])

eigenvalues, eigenvectors = np.linalg.eig(A)
print("Eigenvalues:", eigenvalues)
print("Eigenvectors:n", eigenvectors)
This code snippet initializes the matrix A, computes its eigenvalues and eigenvectors, and prints them out. The output will give us the same eigenvalues we calculated manually, alongside their corresponding eigenvectors, which can be crucial for further analysis or applications.
Moving into practical applications, eigenvalues and eigenvectors are used extensively in various fields. In machine learning, they play a pivotal role in techniques such as Principal Component Analysis (PCA), which reduces dimensionality by transforming data into a new coordinate system based on the directions of maximum variance.
In physics, eigenvalues can represent observable quantities, while within the scope of stability analysis, they help determine the stability of equilibrium points in dynamic systems. The connection between eigenvalues and system dynamics is particularly significant in control theory, where eigenvalues of system matrices can indicate system behavior.
Furthermore, eigenvalues can be used in graph theory, where they help analyze the properties of graphs through their adjacency matrices. The largest eigenvalue of a graph can provide insights into the connectivity and structure of the graph, while the eigenvalues of the Laplacian matrix can indicate clustering and community structure.
When using NumPy, we can explore advanced features in numpy.linalg.eig to handle complex matrices and understand the implications of complex eigenvalues in various scenarios. Complex eigenvalues occur in systems that exhibit oscillatory behavior, which is common in physical systems such as electrical circuits or mechanical vibrations.
A_complex = np.array([[0, -1],
                      [1, 0]])

eigenvalues_complex, eigenvectors_complex = np.linalg.eig(A_complex)
print("Complex Eigenvalues:", eigenvalues_complex)
print("Complex Eigenvectors:n", eigenvectors_complex)
This example illustrates how NumPy efficiently computes eigenvalues and eigenvectors even when dealing with complex matrices. Understanding these results is important as they provide insights into the behavior of systems represented by such matrices.
Overall, the use of NumPy for linear algebra tasks not only simplifies the computation of eigenvalues and eigenvectors but also extends to a wide range of applications across different domains. This versatility makes it an essential tool in the toolkit of any data scientist or engineer working with linear transformations, system dynamics, or data analysis.
Continuing with the exploration of eigenvalues and eigenvectors, we can leverage NumPy’s capabilities to handle larger matrices and more complex scenarios. For instance, consider a scenario where we need to analyze a 3×3 matrix, which is common in many practical applications.
B = np.array([[1, 2, 3],
              [0, 1, 4],
              [0, 0, 1]])
Using NumPy to compute the eigenvalues and eigenvectors of this matrix is simpler, as shown below:
eigenvalues_B, eigenvectors_B = np.linalg.eig(B)
print("Eigenvalues of B:", eigenvalues_B)
print("Eigenvectors of B:n", eigenvectors_B)
This allows us to quickly analyze the properties of matrix B without delving into the cumbersome calculations manually. The eigenvalues here can provide insights into the stability of systems modeled by this matrix.
Another practical application of eigenvalues is in the field of image processing. Techniques such as image compression often use eigenvalues and eigenvectors to reduce the dimensionality of image data while preserving essential features. For example, Singular Value Decomposition (SVD) is a method that relies on the eigen decomposition of matrices to achieve efficient image representation.
from numpy.linalg import svd

image_matrix = np.random.rand(256, 256)  # Simulated image data
U, s, Vt = svd(image_matrix)

# Keep only the top k singular values for compression
k = 50
compressed_image = np.dot(U[:, :k], np.dot(np.diag(s[:k]), Vt[:k, :]))
This code snippet demonstrates how to perform SVD on an image matrix, retaining only the top k singular values for a compressed representation. The eigenvalues derived from the SVD can help determine how many components are necessary to retain the most significant features of the image.
Furthermore, in the context of network analysis, eigenvalues can help identify influential nodes and their connectivity within a network. The eigenvector centrality metric, derived from the principal eigenvector of the adjacency matrix, provides a way to measure the influence of each node based on the connectivity of its neighbors.
import networkx as nx

G = nx.erdos_renyi_graph(100, 0.1)  # Create a random graph
L = nx.normalized_laplacian_matrix(G).A  # Compute the normalized Laplacian
eigenvalues_L, eigenvectors_L = np.linalg.eig(L)

# The principal eigenvector can be used for centrality measures
principal_eigenvector = eigenvectors_L[:, np.argmax(eigenvalues_L)]
This snippet shows how to compute the principal eigenvector of the normalized Laplacian matrix of a graph, which can be interpreted as the centrality measure for the nodes within the network.
As we delve deeper into the applications of eigenvalues and eigenvectors, it becomes evident that their utility spans across diverse fields such as quantum mechanics, where they are used to solve the Schrödinger equation, and in finance, where they can model risk and return structures in portfolio management.